The Language of Accounting: Disconnect between Accountants and Bookkeepers

The Language of Accounting: Disconnect between Accountants and Bookkeepers

There are a tremendous number of bookkeeper training programs developed over the years which propose to deliver the essential bookkeeping knowledge (e.g., double entry accounting) required in order to properly service business bookkeeping requirements.  Particularly as the CPA profession stepped away from traditional bookkeeping in favor of performing “higher level” and more profitable work, there was and continues to be a great need for skilled and experienced bookkeepers.  While it seems that accountants and bookkeepers would be a natural fit for partnering to serve small business client needs, there is often a disconnect between the two which causes the working relationship to not always prove as beneficial as it could.  What is the cause of this disconnect?  In many cases, it is due to the fact that the bookkeeper training educated the operator on the use of a software product, and not on the fundamentals of accounting and bookkeeping.

Over the past few years, I have had the opportunity to look through a lot of bookkeeper training programs, and the thing that stands out is that many of these programs aren’t really training bookkeepers on accounting principles.  More frequently, the training is focused on teaching users how to use software (usually QuickBooks).  With the number of users of the QuickBooks product, it is obvious that there is a need to educate users on the solution because people need to know how to use their software properly.  But it happened at some point in time that a majority of the industry came to believe that learning QuickBooks (or Xero or Freshbooks or Kashoo or whatever) was somehow synonymous with learning bookkeeping.

When I first started working with my father in his accounting practice, I had to use a manual general ledger, check register, etc.  It was all manual – computers didn’t come along for a while (yes, I am that old).  It was time-consuming, but it taught me the fundamentals.  I know what a subledger is.  In consumer-friendly software like QuickBooks, you don’t work in the AR subledger; you push the button that says “customers” or maybe “invoices”.   QuickBooks, in many ways, doesn’t speak accounting.  It speaks record keeping.  And this is where the disconnect begins.

An old school accountant will recall the green eye shade days and working with book ledgers and 13-column pads, but even “new” school accounting professionals know that the fundamentals of accounting aren’t available for re-invention.  A debit is still a debit and a credit is a credit.  Yes, there are intimacies involved which speak to specific treatment of items for reporting and tax purposes, etc., but the essentials of double entry and other basic accounting principles are consistent and unchanging.

The “language of accounting” includes certain precise terms with specific meaning, and this precision in the use of terms simply doesn’t exist in many bookkeeper training programs. Rather than focusing on the fundamental accounting training bookkeepers truly need in order to be of maximum value to the business, these programs focus on helping users become experts in using the software product, or even to become experts at teaching others how to use the solution.  While this software expertise may be beneficial in terms of helping accountants work with their clients who use the software, it doesn’t add enough value to the relationship to warrant partnering.  What accounting professionals need are bookkeepers who understand bookkeeping and who can apply basic accounting principles to the task.  Which software they operate is secondary to that purpose.

Professional bookkeepers, accountants, and the business client are all in a position to benefit tremendously when the service providers team up to provide comprehensive service.  The key to making these connections lies with the professional bookkeeper who must not only understand basic accounting principles, but must also be able to speak to the accounting professional in their native language.
Make Sense?

J

read more…

Opinion:   I think that every QuickBooks training program should include taking the sample data file in QuickBooks, and translating that to a manual accounting system of book ledgers and reports.  Then, have the student process a years’ worth of transactions manually and from paper-based source materials (and also make them create and use a manual paper filing system for all that information, and come up with a means to travel to obtain all the documents necessary which aren’t mailed via USPS).  The requirement would include generating the bank reconciliations from printed bank statements and cancelled check copies, creating a trial balance from the general ledger and then creating the P&L and Balance Sheet.  I’ll bet you end up with a group of bookkeepers who better understand the fundamentals of the accounting process.  The other benefit is that these folks will have a much better understanding of the problems in the outsourced accounting model which can be directly addressed and solved by today’s cloud and connected solutions.


The Small Business Borrower | Biz2Credit

In order for regulation and legislation to work in favor of small businesses, it becomes essential that accurate and complete information be available for analysis. Too often there are details not recognized in the information used by various agencies to help guide policy and action, and particularly in the world of privately held small business, the quality of data is often in question. This is where structured accounting software and the public accountant come in to play, and where a difference can be made not only with the individual client, but at a higher level by facilitating more accurate data production to support various research initiatives, such as those sponsored through the SBA and the Fed.

Overall, these research studies highlight two things: the important role that financial institutions play in lending to small business owners, and the value of quality data sets in ascertaining financing issues faced by small businesses and their owners.

Charles Ou, Ph.D. | Senior Economist | Office of Advocacy | July 2009

With the availability of highly useful tools for monitoring various key performance indicators and metrics in the business (with analysis of cash flow being an essential part), business owners and their accounting professionals alike are able to use real business data to reveal not simply the trends in business performance, but to identify areas where direct action could improve results in one aspect or another. By paying closer attention to managing business finances and analyzing key aspects of business performance, the “discouraged” or “denied” business borrower may become a successful or (even more valuable) a non-borrower.

via The Small Business Borrower at Biz2Credit.com.

Technology and Tools for Accounting Professionals

Joanie Mann Bunny FeetTechnology and Tools for Accounting Professionals

old_school_ledgerThere was a time not so long ago when accounting professionals focused more on tabulation and summarizing of information than on analysis.  Accounting for businesses, in particular, required collecting myriad papers and receipts and other transaction documents, summarizing the information, translating it into journal entries, and finally posting those numbers to the big bound book which represented the business general ledger.  With the work required to gather and enter all of the information, professionals necessarily focused their efforts on making the process as efficient as possible by attempting to structure the workflow and manage the paper.
When those efforts are compared to today’s approach which involves digital documents, intelligent data collection tools, automated workflow solutions, online accounting and data analysis, it is clear that the processes for accounting for business activities have not really become simpler.  In fact, much of the enabling technology has served to complicate certain processes, which drives users to find even more “solutions” to address these new problems.  It (IT) is a bit like the Wonka Everlasting Gobstopper, which never gets finished and never gets smaller.  IT simply changes things – regularly and often.

Back then – before the Internet and digital imaging, or even Personal Computers – high technology wasn’t the focus because it didn’t exist in the realm of business in general.  I suppose you could call business solutions at that time “low” technology, where mainly mechanical solutions were introduced to address various business problems.

old_school_filecabinet

As an example, prior to the advent of digital imaging and electronic documents, one of the primary requirements of the business was to organize and store paper documents.  Over time, a wide variety of filing, foldering and labeling solutions have been developed, all oriented towards making the storage and later retrieval of paper documents easier.  For some businesses, letting go of the paper is a hard thing to do.  Years and years of training in keeping paper files has left many business owners and managers wary of working without physical paper documents.  Investments in office space, filing cabinets, storage folders and personnel to organize, file and retrieve all of the documents is only a partial measurement of the cost of managing paper, and large numbers of businesses continue to operate in this manner.

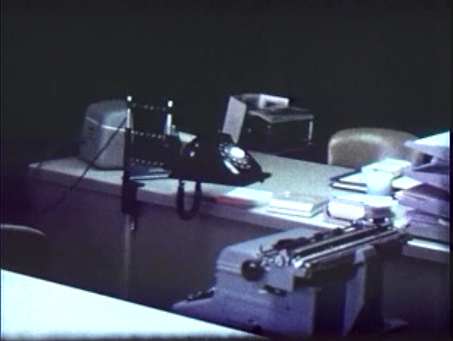
old_school_desk

The technology applied to processing the work has also changed, in many ways even more dramatically than the technology applied to collecting and storing the information.  Take the simple processes of tabulation (to arrange in tabular form; condense and list) and summing (adding up) information, for example.  Previous generations didn’t have computers and spreadsheet software to perform the work.  Rather, individuals would painstakingly handwrite each transaction entry into a ledger or on a columnar worksheet, and would then have to manually add each column and then cross check footer totals to ensure accuracy.  Back then, the machines used to perform the addition/subtraction were mechanical devices and could not perform multiplication or division.   These adding machines were first hand-cranked devices, later replaced with shiny new electrical ones (weighing approximately 20 lbs each).

old_school_telephone

Even voice communications have changed dramatically over the years.  Many people don’t remember a time when having multiple phone lines in the business meant having multiple telephones, and the concept of a PBX (Private Branch eXchange) didn’t exist.  Every phone would be hard-wired to an incoming line; if you wanted to answer a call, you had to use the right phone.  This became difficult in an office with many people, so solutions such as the “fabulous extendo-phone” was invented to allow anyone in the office to access the phone from their desk.

The technology available to businesses today is astounding, and offers amazing potential and benefit.  On the other hand, technology rarely (truly) makes things simple or easy – it more frequently serves to shelter certain users from the complexity while delivering new workloads and concerns to others.  It’s rather like energy – it isn’t created or destroyed, it just changes form [law of conservation of energy].  Business is like that, particularly where information technology is involved.  The underlying requirement doesn’t go away, just like a business’s requirement to account for financial transactions and activities,  and the need for the business to capture and retain documents isn’t changed.  How the process is managed, and which tools or mechanisms are applied to the task is what changes.

Make Sense?

J

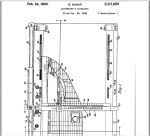
onewrite-accountant_apparatusOne-Write System Revolutionizes Accounting.  These guys had the right idea, they just didn’t have the cloud.

Sustainability and the Humanization of Work

Sustainability and the Humanization of Work

Joanie Mann Bunny FeetFew problems in business are truly solved simply by throwing more money and resources at them.  Certainly, having the people, tools and supplies to get the work done well is a business requirement, and many organizations take a “building out” approach to addressing growing workloads and customer demand.  On the other hand, there are business owners who recognize that things can always be accomplished better and more efficiently, and that improvements in these areas can make the difference between ending up with an overburdened organization with more mass than agility, or a lean organization with the ability to sustain itself while continuously adjusting to meet changing internal and external challenges.

It is said that the only constant is change, and businesses must find a way to effectively and cost-efficiently meet changing demands and conditions in order to survive.  What frustrates many business owners is that change is generally disruptive to the business, representing a significant challenge when it comes to the re-development of internal processes and procedures.   At issue is the understanding that proven, structured and repeatable processes help to improve efficiency, yet changing conditions often require changes to these processes.  In many cases, businesses find that the requirement to structure and document activities is work that must be re-done in the event of broad changes.  Too often, the work falls by the wayside because the minute it is completed, some change comes along and renders it obsolete.  It is somewhat like the child who questions making their bed each day, as they’re just going to sleep in it again and make it messy.

There may be a solution, and a lesson to be learned, in the “kaizen” approach to change and improvement.  Wikipedia’s entry on Kaizen identifies the meaning of the Japanese-Kanji word as simply “good change”.  Similar to the English word “improvement”, kaizen does not refer specifically to any single or ongoing change.  Rather, it has come to describe an approach to business which recognizes the potential for improvement – improvement in work product, work conditions, worker satisfaction, and worker performance – at all levels throughout the enterprise.  Further, kaizen does not describe change as being broad-ranging or particularly intrusive.  Beneficial (good) change may come at any level and may be identified by almost any source.

Kaizen is a daily process, the purpose of which goes beyond simple productivity improvement. It is also a process that, when done correctly, humanizes the workplace, eliminates overly hard work (“muri”), and teaches people how to perform experiments on their work using the scientific method and how to learn to spot and eliminate waste in business processes. http://en.wikipedia.org/wiki/Kaizen

The ultimate business goals are, of course, improved productivity, product quality and profitability.  A “Kaizen” approach to business recognizes that these goals are often met through gaining the participation of the entire organization.  Whether approached as individual effort, small or large group, or via suggestion system, the purpose is to nurture the company’s human resource and help focus it towards making improvements in work environment and activities which lead to improved productivity.  After all, the most valuable asset a business has is its people.  It is logical to apply this individual and collective intelligence and source of business knowledge towards making the company better – and a better place to work.

Make sense?

J

Small Businesses and Performance Data – Analytics are more important than ever

Creating and keeping a competitive edge is critical to building a successful business.  Developing a plan, monitoring the plan to make sure the business remains on target, and setting goals for growth and profitability are foundations of business success.  But great strategy and detailed planning cannot ensure success because the economy and business environments are unpredictable; no amount of planning is a guarantee that bad things won’t happen and the business won’t experience challenges.  On the other hand, regularly monitoring small business performance data can reveal trends and indications that things are not going as expected, and provide a basis for making the decisions necessary to get the business back on track and regain the competitive edge.

Business owners must be prepared to make adjustments as conditions change, acting on decisions made based on business performance data.  While business analytics are more important than ever, with businesses facing volatility in financial markets and increasingly globalized competition, finding a way to approach the matter is often the biggest barrier.  The growing difficulty – the increasingly expanding problem facing business owners and their advisors – can be distilled down to three particularly noticeable trends.

An Aberdeen Group report from Nov 2011 titled “The Analytical SMB” identifies these trends as More Data, More Users and Less Time.

More Data

  1. The volume of data flowing into organizations is already high and is increasing.
    1. The data is complex
    2. The data lacks similarity (data is disparate)

The volume of information flowing in to businesses is already high, and is increasing steadily.  With all the data collection applications and tools available, and as the business seeks to gain more information and intelligence from more sources, the volume of information gathered by businesses has increased at astounding rates.  Technology has adapted to this need, allowing businesses to gather than store vast amounts of data.  To be of value, however, the data must be analyzed to find the answers to questions posed.  What technology is only now beginning to address is the complex and disparate nature of the collected data.  Coming from varying sources and in equally varying formats, data must be “normalized” and related for it to make much sense.

More Users

  1. More business decision makers in more job roles and functions are getting involved
    1. More people approaching the problem with their own “brand” of analysis

In a very small business, decisions are generally made by the owner.  This is most often due to the fact that the owner is the person who not only knows what’s going on in the business, but is generally the one doing a lot of the work.  As businesses grow and bring in personnel to manage various functions, these managers become decision-makers.  Decisions are made in businesses at all levels, and as management layers are compressed, those “closer to the action” are being handed more responsibility for the decisions impacting their areas.   Without a comprehensive and company-wide framework for data analysis and reporting, these individuals and workgroups find ways to capture and analyze the data they feel is pertinent to their requirement and within their own realm.

Less Time

  1. Timeframe for making decisions is shrinking, and is shrinking at an “alarming” rate
    1. The “velocity” (rapidity of motion) of business is increasing

It may be that, in some businesses and markets, certain decisions don’t have to be made with any great speed.  Businesses or markets of this type are tough to find these days because the Internet, information technology and connected systems have all but eliminated the effects of time and distance. Just about everything in business today moves at a rapid pace, and that means that business decisions are often demanded on-the-spot, providing little time for detailed consideration and working through the problem.   Without the tools and data providing meaningful real-time visibility into business performance, decision-makers may be able to act fast but not wisely, and are most frequently guided by their “gut feel” as to what the right move is.

Driving Small Business Analytics

Business decision makers are now recognizing the need to know more about the business and how it is operating and competing in order to effectively address the choices and decisions faced each day.   The cause for this recognition may be due to variable elements, but the conclusion reached was the same: good business decisions require business analytics to support them.

Not surprising was the report finding – that the majority of small business owners felt pressured to adopt a business analytics solution primarily due to the fact that “critical business decisions rely too much on “gut feel”.  Surprise! Other drivers listed were lack of visibility into operational metrics, the growing number of people in the business who want analytical capability, the business’s inability to identify and act upon business opportunities, and having less time to make decisions.

Steps to Get There

As with any business project, there are “degrees of success”, and the ultimate success of a business initiative requires that all parties be on board with it.  Businesses who recognize a need to improve their analytical capability, but who do not then empower their systems, processes and people, will not achieve the same result as those who do.

Focusing on the business data, it is important to address both the volume and disparity by creating formal data management practices and policies, and implementing systems and processes which assist with the intelligent capture and storage of business information.  Simply retaining the data is not useful; it must be presented and applied in a meaningful manner for it to become useful as decision-supporting information.  The value of the information increases dramatically when it becomes truly useful to the business.  Additionally, by empowering a broader framework for data collection and analysis, businesses extend the “intelligence” to others in the organization, supporting individual and workgroup efforts to make better decisions for their respective areas of responsibility.  Of course, if the information is not provided in a timely manner, its value is reduced if not eliminated (hindsight may be 20/20, but that doesn’t help you see where you going to step next).  Any approach to building business intelligence should leverage connectivity and integration to provide a timely delivery of complete information how and when it is needed.

What’s the Proven Benefit?

source: article
source: article

The obvious benefit of business analysis is that business owners are provided with data to help them understand more about the business operational and financial performance.  The real and proven benefit is that the information provides a basis for gaining insight into trends and conditions which impact performance, and which support making the necessary decisions which facilitate improvement in various business areas.

The highest level of proven benefit, according to the Aberdeen Group report, was achieved by those businesses who embraced the requirement to know more about the organization and operation, and who implemented a focused effort at building business intelligence.

Fast Facts: Best-in-Class SMBs Achieved 24% year over year increase in new customer accounts sold compared to 12% for the industry average, and 11% for the laggards.

These organizations which achieved the greatest improvement operated from real data rather than being guided by gut and emotion, enabled the entire organization to participate in the development of organizational and business intelligence, positioned themselves to identify and act on new business and market opportunities, and ensured that those who must make decisions have the information and insightful data to support making the right ones.

Make Sense?

J

read more about


Philosophy of Process Improvement: Today’s CFO Focusing on Operations

Philosophy  of Process Improvement: Today’s CFO Focusing on Operations

There are a great many methodologies and approaches to “making businesses better” through process improvement.  From SixSigma to Continuous Process Improvement to Total Quality Management – all describe methods of measuring performance and outcomes to return intelligence oriented towards improvement.  Many of these approaches are generally applied in manufacturing businesses, because in manufacturing it’s easier to see where processes may be flawed because the process works with tangible elements.  Making corrections in a process can improve the performance of that process by reducing errors or increasing efficiency.  The truth of the matter is that every business is like a manufacturing business, and applying measurements to the various processes the business performs can reveal the secrets to improving not only process performance and product quality, but resultant profitability.

A recent article on CFO.com  titled Operations Take Center Stage, author David McCann discusses how some CFOs are improving business profitability and performance by delving deeper into operational areas of the business, and not remaining focused squarely on accounting and finance issues.

“Operations is the key to everything,” says Larry Litowitz, finance chief at SECNAP Network Security, a secure Internet-services provider. “That orientation is found most at manufacturers, but it should be at every company.”

Fiscal and financial matters are important to every business, but focusing on accounting for the end-result of business activities assumes that the work leading to the result is useful and effective.  As more attention is paid to conservation of cash, reduction of expenses, and overall profit improvement, CFOs are necessarily moving deeper into the operational aspects of the business to uncover potential not previously addressed.  In some cases, the move is more a function of self-defense and necessity than desire, as businesses increasingly compress spending on management, merging the functional roles of CIO, COO and CFO.

Increasingly, CFOs may find themselves taking on operational tasks whether they want to or not. At larger companies, the steady waning of the chief operating officer position has resulted in more operational responsibility for CFOs, recruiters say. In 2000, 47% of the 669 companies included in either the Fortune 500 or S&P 500 had COOs; in 2012, only 35% did, according to executive-recruiting firm Crist Kolder’s 2012 “Volatility Report of America’s Leading Companies.”

Some accounting professionals may believe that they don’t have the skills and experience to suggest changes in operational areas of their client businesses.  I would suggest that logic and reason are generally the prevailing factors supporting process improvement – reasoning that is often developed through simple observation.  Taking the time to understand what the business is doing at each level, and then actually observing those activities and accounting for their effectiveness and error rate, is how professionals can spend quality time in the business and uncover hidden profit potential.

Litowitz says CFOs can influence operations at a range of companies, including service-oriented businesses. “It’s really no different. The work is a set of activities,” he insists… “All these activities can be analyzed, controlled, and measured against a predetermined standard,” says Litowitz. And just as on a manufacturing floor, efficiency generates profit, justifying the CFO’s involvement.

Make Sense?

Joanie Mann Bunny FeetJ