Financial Literacy and Small Business Success

Businesses and individuals alike must make complicated financial decisions throughout their lives.  Sadly, the volumes of research which explore aspects of financial and debt “literacy” among individuals and small business owners reflects that a growing portion of the population lacks the understanding to make these decisions.  Questions surrounding this issue often focus on the educational aspects, and the positive impacts which might be created through greater levels of understanding of accounting fundamentals and the basics of financial management.  Particularly in smaller businesses, where there is a much closer relationship between business and personal finances, understanding even basic financial concepts is likely to lead to “better financial decisions and household well-being”.

a strong relationship between debt literacy and both financial experiences and debt loads[1]

Because many educational offerings tie to specific training approaches and methodologies, it becomes very difficult to measure the usefulness of the skills developed separately from the effectiveness of the training methodology.   Trainers may employ specific devices or tools which facilitate their delivery, and often times these tools become more of a focus than the actual educational content.  On the other hand, a program might provide a great deal of information in a fairly raw form, yet this information is unlikely to deliver a useful result if the participants do not understand it or cannot grasp the concepts introduced. The challenge is not only with providing the education, but finding a balance with the information and the outcomes; understanding how basic the training might be and still provide a measurable, beneficial impact.

In the study Keeping it Simple: Financial Literacy and Rules of Thumb, the authors discuss the benefits of teaching small business owners a series of fundamental “rules of thumb” for management of the business, rather than delving into the complexities of comprehensive business accounting and finance.  Teaching participants about the basics of double entry bookkeeping, cash management and investing, and then coupling that information with instruction on essential processes to follow resulted in significant improvements in financial management and improved the accuracy and consistency of reported data.

the rule-of-thumb training changes actual business management practices[2]


Outcomes show consistently positive when a simpler approach to developing “financial literacy” is provided to small business owners, and particularly when the training and content is oriented towards the characteristics of the participants.   The highest level of result was achieved with business owners with a low level of financial “sophistication”, with a limited interest in financial or accounting training, and with limited baseline business practice structure.  These were the participants who were found to be most likely to implement what they learned in the “rule of thumb” training.

The conclusion drawn from these discussions is that financial education and basic accounting training can become a key factor in helping business owners not only account and report better for their businesses, but provides an essential foundation for understanding how to grow the business and create profitability.   Accounting professionals working with small business clients should recognize that an effort to provide a level of education to clients is likely to not only help those clients make better business (and personal) financial decisions, it will also increase the chances that the client will keep better books and provide the accounting professional with more consistently useful information to work from.

After all, the goal of the accounting professional working with small business clients is to help those small businesses become successful businesses, isn’t it?
Joanie Mann Bunny FeetMake Sense?

J


[1] http://www.nber.org/papers/w14808.pdf

Debt Literacy, Financial Experiences, and Overindebtedness | Annamaria Lusardi and Peter Tufano| NBER Working Paper No. 14808|March 2009

[2] https://www.poverty-action.org/sites/default/files/kis-dfs-march2013_0.pdf | Keeping it Simple: Financial Literacy and Rules of Thumb | By ALEJANDRO DREXLER, GREG FISCHER, AND ANTOINETTE SCHOAR

The Language of Accounting: Disconnect between Accountants and Bookkeepers

The Language of Accounting: Disconnect between Accountants and Bookkeepers

There are a tremendous number of bookkeeper training programs developed over the years which propose to deliver the essential bookkeeping knowledge (e.g., double entry accounting) required in order to properly service business bookkeeping requirements.  Particularly as the CPA profession stepped away from traditional bookkeeping in favor of performing “higher level” and more profitable work, there was and continues to be a great need for skilled and experienced bookkeepers.  While it seems that accountants and bookkeepers would be a natural fit for partnering to serve small business client needs, there is often a disconnect between the two which causes the working relationship to not always prove as beneficial as it could.  What is the cause of this disconnect?  In many cases, it is due to the fact that the bookkeeper training educated the operator on the use of a software product, and not on the fundamentals of accounting and bookkeeping.

Over the past few years, I have had the opportunity to look through a lot of bookkeeper training programs, and the thing that stands out is that many of these programs aren’t really training bookkeepers on accounting principles.  More frequently, the training is focused on teaching users how to use software (usually QuickBooks).  With the number of users of the QuickBooks product, it is obvious that there is a need to educate users on the solution because people need to know how to use their software properly.  But it happened at some point in time that a majority of the industry came to believe that learning QuickBooks (or Xero or Freshbooks or Kashoo or whatever) was somehow synonymous with learning bookkeeping.

When I first started working with my father in his accounting practice, I had to use a manual general ledger, check register, etc.  It was all manual – computers didn’t come along for a while (yes, I am that old).  It was time-consuming, but it taught me the fundamentals.  I know what a subledger is.  In consumer-friendly software like QuickBooks, you don’t work in the AR subledger; you push the button that says “customers” or maybe “invoices”.   QuickBooks, in many ways, doesn’t speak accounting.  It speaks record keeping.  And this is where the disconnect begins.

An old school accountant will recall the green eye shade days and working with book ledgers and 13-column pads, but even “new” school accounting professionals know that the fundamentals of accounting aren’t available for re-invention.  A debit is still a debit and a credit is a credit.  Yes, there are intimacies involved which speak to specific treatment of items for reporting and tax purposes, etc., but the essentials of double entry and other basic accounting principles are consistent and unchanging.

The “language of accounting” includes certain precise terms with specific meaning, and this precision in the use of terms simply doesn’t exist in many bookkeeper training programs. Rather than focusing on the fundamental accounting training bookkeepers truly need in order to be of maximum value to the business, these programs focus on helping users become experts in using the software product, or even to become experts at teaching others how to use the solution.  While this software expertise may be beneficial in terms of helping accountants work with their clients who use the software, it doesn’t add enough value to the relationship to warrant partnering.  What accounting professionals need are bookkeepers who understand bookkeeping and who can apply basic accounting principles to the task.  Which software they operate is secondary to that purpose.

Professional bookkeepers, accountants, and the business client are all in a position to benefit tremendously when the service providers team up to provide comprehensive service.  The key to making these connections lies with the professional bookkeeper who must not only understand basic accounting principles, but must also be able to speak to the accounting professional in their native language.

Make Sense?

J

read more…

Opinion:   I think that every QuickBooks training program should include taking the sample data file in QuickBooks, and translating that to a manual accounting system of book ledgers and reports.  Then, have the student process a years’ worth of transactions manually and from paper-based source materials (and also make them create and use a manual paper filing system for all that information, and come up with a means to travel to obtain all the documents necessary which aren’t mailed via USPS).  The requirement would include generating the bank reconciliations from printed bank statements and cancelled check copies, creating a trial balance from the general ledger and then creating the P&L and Balance Sheet.  I’ll bet you end up with a group of bookkeepers who better understand the fundamentals of the accounting process.  The other benefit is that these folks will have a much better understanding of the problems in the outsourced accounting model which can be directly addressed and solved by today’s cloud and connected solutions.


The Small Business Borrower | Biz2Credit

In order for regulation and legislation to work in favor of small businesses, it becomes essential that accurate and complete information be available for analysis. Too often there are details not recognized in the information used by various agencies to help guide policy and action, and particularly in the world of privately held small business, the quality of data is often in question. This is where structured accounting software and the public accountant come in to play, and where a difference can be made not only with the individual client, but at a higher level by facilitating more accurate data production to support various research initiatives, such as those sponsored through the SBA and the Fed.

Overall, these research studies highlight two things: the important role that financial institutions play in lending to small business owners, and the value of quality data sets in ascertaining financing issues faced by small businesses and their owners.

Charles Ou, Ph.D. | Senior Economist | Office of Advocacy | July 2009

With the availability of highly useful tools for monitoring various key performance indicators and metrics in the business (with analysis of cash flow being an essential part), business owners and their accounting professionals alike are able to use real business data to reveal not simply the trends in business performance, but to identify areas where direct action could improve results in one aspect or another. By paying closer attention to managing business finances and analyzing key aspects of business performance, the “discouraged” or “denied” business borrower may become a successful or (even more valuable) a non-borrower.

via The Small Business Borrower at Biz2Credit.com.

via Accounting and Business Technologies | QuickBooks Pro and Premier as Software-as-a-Service

QuickBooks Pro and Premier as Software-as-a-Service

Running business applications online was once considered a fad, but has now become a mainstream approach to implementing technology. Businesses large and small are finding that turning technology investments into a predictable expense allows them to focus on their business operations and not the IT budget. For some, the ability to bring remote locations or mobile team members closer to the systems that support the business is the biggest benefit. For others, the security of having business continuity and disaster recovery built into the system is the key. Regardless of the motivating factors, business owners are finding that online application services can make a positive impact to their bottom line.

The market has clearly identified online technologies and application services as something beneficial. This is demonstrated by the rapid adoption and growth of business solutions that leverage the Internet as network. Further, online applications and services are being used as a way to augment systems that were once exclusively LAN or PC based. An example of this is the extension of Intuit’s QuickBooks products to incorporate online payroll services and online payment processing solutions.

With the move to online application services being one of the biggest shifts in technology seen in years, it only makes sense that the applications that have become “standards” in business shift to an online model, as well. The opportunity is great, but the responsibility is greater.

Many software companies are facing a number of problems with respect to the unauthorized hosting of their desktop applications. Because of the technology employed for desktop application hosting is very costly, many service providers feel compelled to “leverage” application licensing and other system features to increase their value proposition and in order to compete. Customers who utilize these unauthorized application services are putting their businesses at potential risk. This risk may come in the form of substandard services resulting in lost or corrupted data; risk may come in the form of unauthorized access to confidential business or personal information due to poor system security; risk may come in the form of exposure due to the unauthorized use of software licenses.

While the market has clearly demonstrated the value and benefit of application hosting services, the lack of protections, consistency and support make it a venture fraught with peril for many. The volume of “grey market” activity and instances of license piracy have undoubtedly increased dramatically, as the cost of service delivery is high and the margins for the service provider are narrow. Manipulating the cost of service by leveraging the application licensing is sometimes the only way some service providers can create profitability in their offerings. But with the prior lack of oversight in terms of service pricing, licensing, quality assurance, or service orientation, it had become the “wild west” for service providers, and the perceived value of the service declined while the number of and variety of deliveries increased.

The answer to the problem, or at least as it exists around the Intuit QuickBooks products, is in the ability for Intuit-Authorized QuickBooks hosting providers to offer subscription access to QuickBooks Pro and Premier licenses when they are hosted. Customers no longer need worry about purchasing their QuickBooks software before engaging with the hosting company, and can avoid the annual cost of upgrading their application software. With the QuickBooks license delivered under a subscription program, customers are able to work with the most current version of the software, and know that their systems are protected and their data is secure. Intuit-authorized QuickBooks Hosting providers can supply, manage, and maintain hosted QuickBooks implementations for businesses of virtually any size and type – all with an Intuit-supported license.

via Accounting and Business Technologies | Joanie Mann: QuickBooks Pro and Premier as Software-as-a-Service.

Technology and Tools for Accounting Professionals

Joanie Mann Bunny FeetTechnology and Tools for Accounting Professionals

old_school_ledgerThere was a time not so long ago when accounting professionals focused more on tabulation and summarizing of information than on analysis.  Accounting for businesses, in particular, required collecting myriad papers and receipts and other transaction documents, summarizing the information, translating it into journal entries, and finally posting those numbers to the big bound book which represented the business general ledger.  With the work required to gather and enter all of the information, professionals necessarily focused their efforts on making the process as efficient as possible by attempting to structure the workflow and manage the paper.
When those efforts are compared to today’s approach which involves digital documents, intelligent data collection tools, automated workflow solutions, online accounting and data analysis, it is clear that the processes for accounting for business activities have not really become simpler.  In fact, much of the enabling technology has served to complicate certain processes, which drives users to find even more “solutions” to address these new problems.  It (IT) is a bit like the Wonka Everlasting Gobstopper, which never gets finished and never gets smaller.  IT simply changes things – regularly and often.

Back then – before the Internet and digital imaging, or even Personal Computers – high technology wasn’t the focus because it didn’t exist in the realm of business in general.  I suppose you could call business solutions at that time “low” technology, where mainly mechanical solutions were introduced to address various business problems.

old_school_filecabinet

As an example, prior to the advent of digital imaging and electronic documents, one of the primary requirements of the business was to organize and store paper documents.  Over time, a wide variety of filing, foldering and labeling solutions have been developed, all oriented towards making the storage and later retrieval of paper documents easier.  For some businesses, letting go of the paper is a hard thing to do.  Years and years of training in keeping paper files has left many business owners and managers wary of working without physical paper documents.  Investments in office space, filing cabinets, storage folders and personnel to organize, file and retrieve all of the documents is only a partial measurement of the cost of managing paper, and large numbers of businesses continue to operate in this manner.

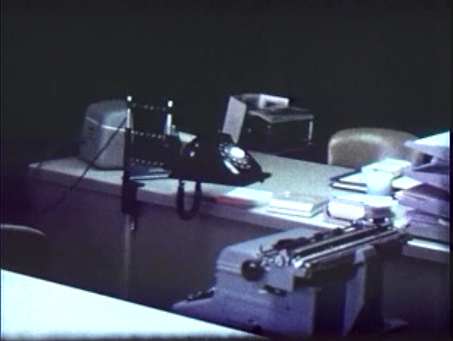
old_school_desk

The technology applied to processing the work has also changed, in many ways even more dramatically than the technology applied to collecting and storing the information.  Take the simple processes of tabulation (to arrange in tabular form; condense and list) and summing (adding up) information, for example.  Previous generations didn’t have computers and spreadsheet software to perform the work.  Rather, individuals would painstakingly handwrite each transaction entry into a ledger or on a columnar worksheet, and would then have to manually add each column and then cross check footer totals to ensure accuracy.  Back then, the machines used to perform the addition/subtraction were mechanical devices and could not perform multiplication or division.   These adding machines were first hand-cranked devices, later replaced with shiny new electrical ones (weighing approximately 20 lbs each).

old_school_telephone

Even voice communications have changed dramatically over the years.  Many people don’t remember a time when having multiple phone lines in the business meant having multiple telephones, and the concept of a PBX (Private Branch eXchange) didn’t exist.  Every phone would be hard-wired to an incoming line; if you wanted to answer a call, you had to use the right phone.  This became difficult in an office with many people, so solutions such as the “fabulous extendo-phone” was invented to allow anyone in the office to access the phone from their desk.

The technology available to businesses today is astounding, and offers amazing potential and benefit.  On the other hand, technology rarely (truly) makes things simple or easy – it more frequently serves to shelter certain users from the complexity while delivering new workloads and concerns to others.  It’s rather like energy – it isn’t created or destroyed, it just changes form [law of conservation of energy].  Business is like that, particularly where information technology is involved.  The underlying requirement doesn’t go away, just like a business’s requirement to account for financial transactions and activities,  and the need for the business to capture and retain documents isn’t changed.  How the process is managed, and which tools or mechanisms are applied to the task is what changes.

Make Sense?

J

onewrite-accountant_apparatusOne-Write System Revolutionizes Accounting.  These guys had the right idea, they just didn’t have the cloud.

Cloud IT: Hiding Complexity and Risk

jmbunnyfeet

Cloud IT: Hiding Complexity and Risk

Cloud computing and Internet technologies have delivered previously unimagined capability for even the smallest of businesses – capability to compete, build brand recognition, and reach markets in remote geographies.  The mantra for businesses used to be “location, location, location”, but it’s become connectivity – perhaps even more than location – which now delivers business opportunity.  As technology has evolved, allowing businesses and consumers to connect regardless of time or place, the complexity of the systems and networks have also increased dramatically.  Where a business could once easily identify their various vendors or business service providers, the identification of those involved in the service ‘delivery chain’ are no longer so easily recognized.   Among the benefits of cloud computing technologies is the ability to reach beyond traditional boundaries.  The risk for many businesses is in not fully understanding how, and with whom, those boundaries are being crossed.

For many an enterprise, the convenience and efficiency introduced with cloud computing models overshadows the increased risk potential.  Service level agreements and vendor contracts are assumed to be sufficient to protect the business and its information assets, yet recent events (such as the recent reveals of PRISM and the actions of the National Security Agency) should cause businesses to look a little deeper at their entire provider network.  It’s not that the average business should be concerned about government snooping of their emails, but they should be aware of who has access to their systems and data, and which entities are responsible for which parts of the system.  It’s only prudent to know the details, and it is the best first step to mitigate business risk.

Enterprise Clouds are complex, sophisticated entities which invariably rely on a daisy-chain of third parties and contractors to help build, run and maintain their Cloud provider’s systems. The organizational and technical complexities are additive, resulting in increased systemic risk. Systemic risk is the least visible and hardest to eliminate, and those risks become real when the providers’ systemic risks become [yours].

The question is, how well does your Cloud provider manage the ecosystem of contractors and third parties that are farther down the food chain? This is even more relevant in the globalized workforce, where, paradoxically, Cloud and related technologies have greatly facilitated the outsourcing and offshoring of work to low-cost countries. http://www3.cfo.com/article/2013/6/data-security_prism-national-security-agency-edward-snowden-cloud-implications-vendor-management

Before executing a service agreement with an outsourced provider, make certain that the details of facility, connectivity, network, equipment, and other elements of the delivery and system are spelled out.  Business subscribers should know where the various points of failure exist, and which company is responsible for dealing with each.  If a carrier fails and connectivity to the data center is lost, the hosting service provider may be powerless to impact the situation, even though access to service is part of the SLA and requirement.  If a hosted software product has a vulnerability or fails to perform, the developer of the product is likely responsible, rather than a hosting service provider.  The point is that there are often multiple players in the delivery chain, and customers should be aware of this reality prior to engaging with the service.

Ultimately, the business with mission critical data in the possession of a 3rd party service provider should have a healthy helping of doubt as to whether the provider has full control over their environment.  Business owners, managers and CFOs should recognize the increased necessity of evaluating risk within their provider systems and in provider/vendor relationships, to keep trade secrets secret and prevent intellectual property from becoming the property of others.

Joanie Mann Bunny Feet

Make Sense?

J